Hausman-Kunkel InsuranceHausman-Kunkel Insurance
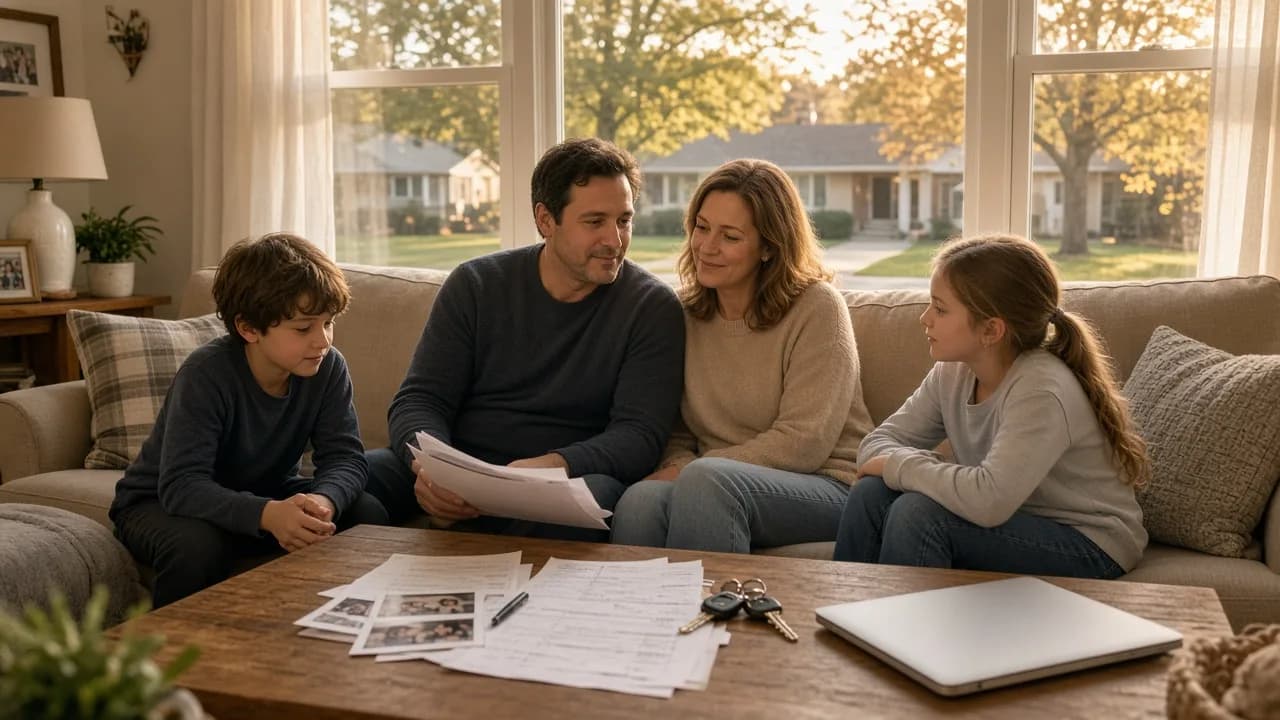
Suburban Illinois family in a living room with mortgage papers, a laptop, and kids on the sofa

Individual Life Insurance

Solutions to ensure your loved ones have what they need

Income replacement

The check that keeps the household running if a breadwinner dies.

Most Illinois families buy life insurance so a mortgage, childcare, and groceries do not land on the surviving spouse overnight. We size the death benefit from income, debts, and how long dependents still need support — not a round multiple of salary.

Learn more →

Tap a point on the scene to learn more

Pin the add-ons that match how you use this coverage

The base life insurance policy is the printed form. An is a taped-on change — adding coverage, taking it away, or renaming who is insured. Optional coverages ride along with the policy. Separate policies sit beside it.

Form names and availability vary by carrier. This is a map of add-ons we commonly shop in Illinois — not a promise that every company offers every item.

Base policy

Life insurance policy

Hover an add-on to read it, then click to pin it here — a review list for your next conversation with an advisor.

Send this list to an advisor →We’ll open the contact form for this coverage so an advisor can help you decide which add-ons belong on the policy.

1 of 9

Endorsement

Waiver of premium

The policy can stay in force if you meet the disability definition on the form.

A waiver-of- rider can pay life premiums while you are disabled under the contract’s rules. Waiting periods and definitions vary. It is not disability income. We add it when a during a long recovery would leave the household uninsured.

You cannot put a dollar amount on your family, but you can ensure their future is protected. We cannot predict when the unexpected will happen, but we can help you prepare for it when it does.

We will walk through , any for a late payment, and what happens if a policy would so the contract matches the benefit you think you are buying.

The most important investment you can make for your family

Individual life insurance is arguably the biggest investment you can make in your loved ones' security. It is a complicated field, but do not let that put you off. We will be happy to talk you through the options.

Choosing between term, whole, and universal life insurance

First, you will need to determine the type of life insurance you want to buy, with the most common types being term life insurance, whole life insurance, and universal life insurance. Each has its own way of paying out, and the plan you choose can be best determined by your individual needs.

What is term life insurance?

With term life insurance, you pay regular premiums for a set period and the policy only pays out if you die during this period.

What is whole life insurance?

With whole life insurance, there's no set period. You usually pay regular premiums until you die, at which point the policy pays out. Sometimes you have the option to take a lump sum back while you are still alive, but this will reduce the amount paid out when you die.

What is universal life insurance?

Universal life insurance works in a similar way to whole life insurance, but you have more flexibility about taking money early. You can even borrow money and repay it later; although, if there's any loan outstanding when you die, the policy's payout can be significantly affected.

What to consider before getting life insurance

The premiums you pay depend heavily on your age and medical history, along with the amount you want the policy to pay out. So, it is important to seek expert advice before committing to life insurance.

Contact us and we will walk you through the options and help you to determine if term life insurance, whole life insurance, or universal life insurance are right for you.

Request an individual life quote to get started.

Frequently Asked Questions

What does Individual Life Insurance typically provide?
Life insurance may provide income replacement, debt protection, estate liquidity, or legacy planning depending on the policy type. Term and permanent products serve different goals and budgets.
How much life insurance do Illinois families typically need?
Needs depend on income, debts, dependents, and goals. We review household finances and future obligations rather than recommending a one-size-fits-all multiple of salary.
What is the difference between term and permanent life insurance?
Term insurance covers a set period at lower initial cost. Permanent policies may build cash value and last a lifetime but require different and commitments.
Should I review beneficiaries and limits after major life events?
Marriage, divorce, new children, home purchases, and career changes often mean coverage should be updated. Annual reviews help keep policies aligned with your goals.
How does an independent agency help me compare Individual Life options?
As an in Roselle, we compare Individual Life Insurance options from multiple carriers instead of a single company menu. That helps Illinois clients find coverage that fits their risks, contracts, and budget—with local follow-up when questions or claims come up.
What happens when a term policy ends?
Coverage typically stops unless you convert to a permanent product during the window in the contract, or you buy a new policy subject to new . Conversion deadlines are easy to miss. We calendar them when we place Illinois term cases.
What is a waiver of premium rider?
It can keep the life policy in force if you meet the disability definition on the form, so do not during a long recovery. It is not disability income. Waiting periods and definitions vary by carrier.
Can I use a life policy while I am still living?
Some forms include or offer an accelerated death benefit for a qualifying terminal or chronic illness. Using it reduces what beneficiaries receive. It is not a substitute for long-term care insurance. We read the trigger language before anyone counts on it for care bills.
Do I still need individual life insurance if I have group coverage at work?
Group life often ends or shrinks when you leave the job, and the amount may be a flat multiple of salary that does not match a mortgage or young children. We treat workplace life as a layer, then quote an individual policy you control.
How does medical underwriting affect a life insurance quote?
Age, health history, tobacco, and labs can change the class and the . Applying after a new diagnosis is often harder than applying while you are healthy. We prepare the application honestly and shop carriers that still make sense for the risk.

Endorsements and add-ons

The same life insurance policy add-ons from the explorer above, listed out. Form names and availability vary by carrier.

Accelerated death benefit

Optional coverage

Access part of the death benefit while living if a qualifying illness applies.

Many policies include or offer an accelerated benefit for a terminal or chronic illness named in the form. Using it reduces what beneficiaries receive. It is not a long-term care policy. We read the trigger language with Illinois families before anyone counts on it for care bills.

Accidental death

Endorsement

An extra amount if death is caused by a covered accident.

Accidental death (AD&D on some forms) pays an additional benefit for a qualifying accident. Illness does not trigger it. Illinois commute and highway deaths still need the base death benefit sized correctly — this rider is a supplement, not the plan.

Child rider

Endorsement

Modest coverage on listed children, often convertible later.

A child rider can put a small death benefit on each child named on the application. It is not income replacement for a parent. Conversion options, if any, are in the rider. We still quote a separate child policy when the family wants a larger permanent layer.

Learn more →

Chronic illness / LTC-style rider

Endorsement

Some permanent forms let you accelerate benefits for qualifying long-term care needs.

Chronic-illness or long-term-care riders are not identical to a standalone long-term care policy. Triggers, elimination periods, and residual death benefits differ. We compare the rider against a separate LTC conversation instead of treating them as the same product.

Learn more →

Disability income

Separate policy

Replaces paycheck if you cannot work — a different policy from life insurance.

Life insurance pays if you die. Disability income pays if you live and cannot work. A waiver rider on life does not replace a disability check. Illinois professionals and owners often need both. We quote disability as its own contract.

Learn more →

Guaranteed insurability

Endorsement

Buy more coverage later at option dates without proving new health.

A guaranteed-insurability rider lets you increase the death benefit at scheduled ages or events without a new medical exam. Amounts and dates are limited. It helps younger Illinois clients who expect income to rise after a first policy is in force.

Long-term care insurance

Separate policy

Pays for qualifying custodial or facility care — not a life death benefit.

A life rider may help with some chronic-illness needs. A long-term care policy is built for care costs. We do not treat an accelerated death benefit as a full LTC plan. Illinois families who want dedicated care coverage get a separate quote.

Learn more →

Term conversion

Optional coverage

A contractual window to move term coverage to permanent without new exams.

Conversion is how term can become permanent if health changes. Deadlines and eligible permanent products are in the contract. Missing the window is expensive. We calendar conversion dates when we place Illinois term cases.

Waiver of premium

Endorsement

The policy can stay in force if you meet the disability definition on the form.

A waiver-of- rider can pay life premiums while you are disabled under the contract’s rules. Waiting periods and definitions vary. It is not disability income. We add it when a during a long recovery would leave the household uninsured.

Ready for a Quote?

Speak with a local advisor who understands your coverage needs.

  • Geico insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • AAA insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Hartford insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Progressive insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Liberty Mutual insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Travelers insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Safeco insurance quotes through Hausman-Kunkel Insurance in Roselle, IL

Contact Hausman-Kunkel Insurance

As an independent agency, we are here to help you find the right coverage.

Please do not include sensitive, private information in this area.

Get a Quote

It only takes a minute to get started.

  • Fill out the form, we'll be in touch.
  • Go over your options with an agent.
  • Get the coverage you need.

Would you rather discuss this in person? Get in touch with an agent today!

Contact Us