Hausman-Kunkel InsuranceHausman-Kunkel Insurance
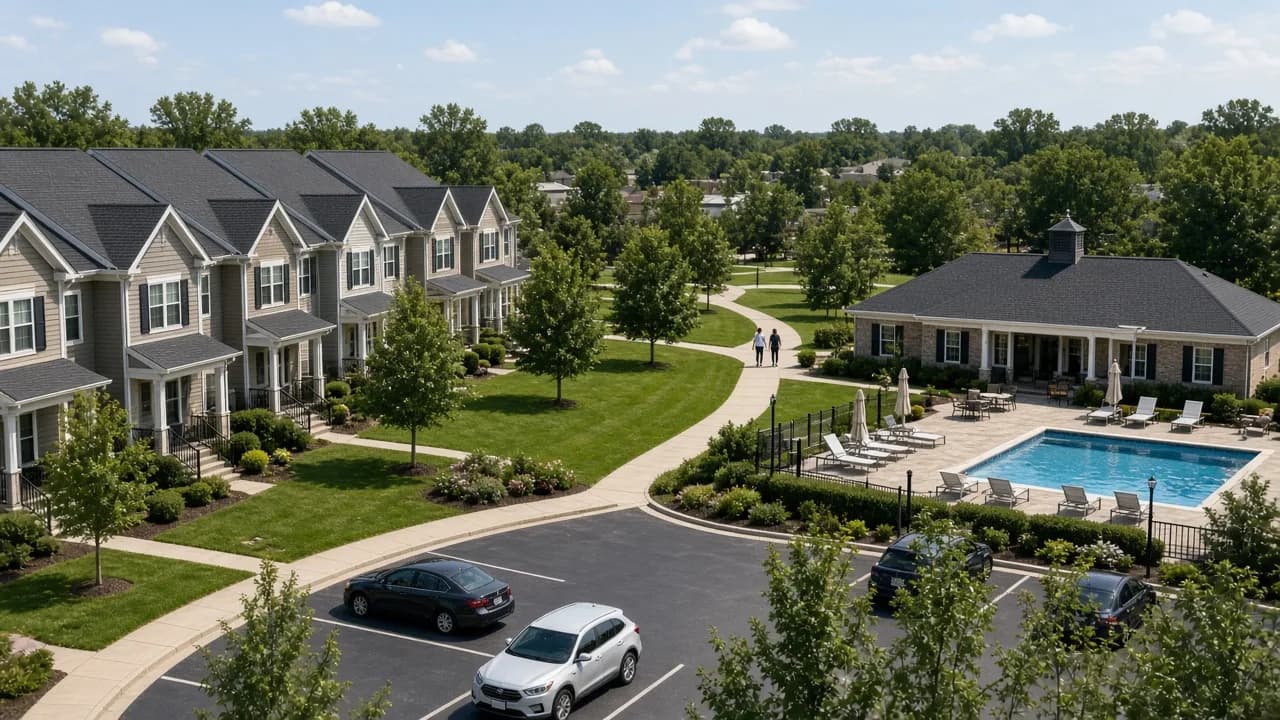
Chicagoland HOA community with townhomes, a clubhouse, landscaped courtyard, pool, and parking

Homeowners Association Insurance

Coverage designed to protect your HOA

Master policy / common building

The structures and shared property the HOA owns.

The HOA master policy insures buildings and common property the association owns — not residents’ furniture. Bare-walls versus all-in wording decides how far into each unit the master goes. Unit owners still need their own HO-6.

Learn more →

Tap a point on the scene to learn more

Pin the add-ons that match how you use this coverage

The base homeowners association policy is the printed form. An is a taped-on change — adding coverage, taking it away, or renaming who is insured. Optional coverages ride along with the policy. Separate policies sit beside it.

Form names and availability vary by carrier. This is a map of add-ons we commonly shop in Illinois — not a promise that every company offers every item.

Base policy

Homeowners association policy

Hover an add-on to read it, then click to pin it here — a review list for your next conversation with an advisor.

Send this list to an advisor →We’ll open the contact form for this coverage so an advisor can help you decide which add-ons belong on the policy.

1 of 10

Separate policy

Directors and officers

Board decisions, assessments, and alleged mismanagement.

is how volunteer board members are meant to be protected when the association is sued over governance. It is not and not a property claim. Illinois HOAs treat this as its own policy, often required by the management contract.
Learn more →

While the homeowners, condo owners, and renters who are part of your homeowners association have their own insurance policies for their personal belongings and owned properties, homeowners associations (HOAs) are responsible for having insurance for properties owned by the HOA, as well as common areas. Because of the many risks HOAs face, it is important to have a specialized homeowners association insurance policy in place.

What insurance coverages do homeowners associations need?

Homeowners associations of all types need insurance, including condominiums, planned communities, and townhouses. One of the most important coverages each of these homeowners associations need is an HOA master policy. This provides coverage against and loss, as well as claims from visitors or HOA members. A commercial property insurance policy offers protection for buildings owned by the HOA, but it is important to note that it only covers the structures, not the personal contents of residents.

The risks that homeowners associations face

Homeowners associations have the responsibility of the safety and well-being of their residents and visitors on property owned by the HOA. For example, if a visitor sustains injuries while at your HOA's common area, your liability coverage would kick in to cover costs from medical claims and potential lawsuits. (D&O) insurance protects the assets of board members if the organization is sued for alleged acts of wrongdoing. Crime insurance can provide coverage to protect your HOA in event of crimes by either a 3rd party or an employee, depending on the policy.

Important things to know about homeowners association insurance

Homeowners association insurance covers structures owned by the HOA, not the personal belongings of the residents. This means that if a resident does not have the appropriate coverage for their personal belongings, it would not be covered under the HOA's policy. The requirements of minimum coverage that HOA members need may vary depending on where your community is located. Your agent will be able to determine what is covered by the HOA and what HOA members are responsible for.

The business side of homeowners associations

There are some policies that your homeowners association needs to consider in order to provide more protection. For example, if you hire employees that perform maintenance and they are injured on the job, would offer coverage for their medical expenses. A insurance policy could benefit the HOA if you store any sort of personal information on your computer network. Also, a social host liability insurance policy is helpful to have if you allow HOA members to host events at HOA owned buildings or common areas, as it provides coverage from potential liability claims.

Do you need specialized homeowners association insurance for your HOA? Contact us to discuss your options.

Request a homeowners association quote to get started.

Frequently Asked Questions

What does Homeowners Association Insurance typically cover?
Industry-specific policies address risks common to homeowners Association operations in Illinois—from property and to specialized . We tailor recommendations to your contracts, equipment, and workforce.
What insurance do homeowners Association businesses in Chicagoland usually carry?
Most need a foundation of and when employees are involved. Property, commercial auto, professional, or coverage may also apply depending on the work you perform.
Can you provide certificates for landlords and project owners?
Most active clients receive ACORD certificates the same business day. We align and waiver language with Chicagoland lease and contract requirements.
What mistakes do homeowners Association operators make when buying insurance?
Underinsured limits, missed , and using personal policies for business activity are common issues. We review operations details so coverage matches how you actually work.
What is the difference between the HOA master policy and a unit owner’s HO-6?
The master insures common buildings and shared property the association owns. Unit owners still need an HO-6 for contents, in the unit, and whatever interior the bylaws leave to them. Bare-walls versus all-in wording on the master decides how far into each unit it goes. We read the bylaws with both policies, not just the certificate.
Do Illinois HOA boards need directors and officers insurance?
Usually yes. is how volunteer board members are meant to be protected when the association is sued over assessments, vendors, or enforcement. It is not and not a property claim. Management contracts often require it. We place D&O beside the master, not as a checkbox on GL.
Does the HOA master policy cover residents’ furniture and belongings?
No. The master covers structures and common property the association owns, not sofas and electronics inside a unit. Residents need their own HO-6 or renters policy. An underinsured owner is not a gap the association can paper over after a fire. We explain both sides when we review a Chicagoland community.
Do homeowners associations need workers compensation?
If the HOA has employees, Illinois generally requires . A landscaper or maintenance worker on payroll who is hurt on the grounds is a WC claim, not GL. 1099 vendors need their own coverage. Misclassification is a board problem. Volunteer directors are a different conversation from employees.
Does the HOA master cover flood and sewer backup on common areas?
Sewer and drain backup is usually an . Flood from a rising body of water is typically excluded and may need a separate flood policy. Chicagoland courtyards and underground garages take both. We treat flood and sewer as two conversations, not one checkbox on the master.
Why use an independent agency for Homeowners Association Insurance?
As an in Roselle, we compare Homeowners Association Insurance options from multiple carriers instead of a single company menu. That helps Illinois clients find coverage that fits their risks, contracts, and budget—with local follow-up when questions or claims come up.

Endorsements and add-ons

The same homeowners association policy add-ons from the explorer above, listed out. Form names and availability vary by carrier.

Commercial umbrella

Separate policy

Extra limit over the master GL after a severe common-area claim.

Pool, sidewalk, and parking-lot claims can exceed a primary GL limit. An sits over the master — and often over auto if the association has vehicles. We size it to the community, not a default.

Learn more →

Crime / fidelity

Endorsement

Theft of association funds by an employee, board member, or vendor.

Assessments sit in a bank account. Crime and employee-dishonesty coverage responds if money walks. GL does not pay embezzlement. Limits should match how much cash the association actually holds between collection cycles.

Cyber liability

Separate policy

Owner lists, gate codes, and the association portal.

HOAs store names, assessments, and sometimes access credentials. A ransomware event is not a burglary claim on the clubhouse. Cyber sits beside the master policy, not inside it.

Learn more →

Directors and officers

Separate policy

Board decisions, assessments, and alleged mismanagement.

is how volunteer board members are meant to be protected when the association is sued over governance. It is not and not a property claim. Illinois HOAs treat this as its own policy, often required by the management contract.

Learn more →

Equipment breakdown

Endorsement

Boilers, elevators, and HVAC that fail suddenly.

Property insurance treats mechanical breakdown as wear and tear. Equipment breakdown is the buyback for a clubhouse boiler, an elevator, or a rooftop unit. Pair it with extra expense if residents cannot use the building without that system.

Flood

Separate policy

Rising water on common property is typically excluded.

Flood from surface water or a nearby creek is usually excluded from the master. Underground garages and low clubhouses in Cook and DuPage still need a separate flood conversation. is a different .

Learn more →

Ordinance or law

Endorsement

Code upgrades after a partial loss to older common buildings.

After a fire in a 1970s clubhouse or masonry building, the village may require sprinklers, electrical, or accessibility work — including demolition of undamaged portions. pays that increment. The base building limit rebuilds what was there.

Sewer backup

Endorsement

Drain backup in a clubhouse or underground garage — not flood.

Sewer and drain backup is an on most master forms. Flood from a rising body of water is typically excluded. Chicagoland courtyards and parking decks take water from drains after a storm. We treat them as two conversations.

Workers compensation

Separate policy

Maintenance employees — not volunteer board members.

If the HOA has employees, Illinois generally requires . A landscaper on payroll hurt on the grounds is a WC claim, not GL. 1099 vendors need their own coverage. Misclassification is a board problem.

Learn more →

Ready for a Quote?

Speak with a local advisor who understands your coverage needs.

  • Geico insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • AAA insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Hartford insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Progressive insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Liberty Mutual insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Travelers insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Safeco insurance quotes through Hausman-Kunkel Insurance in Roselle, IL

Contact Hausman-Kunkel Insurance

As an independent agency, we are here to help you find the right coverage.

Please do not include sensitive, private information in this area.

Get a Quote

It only takes a minute to get started.

  • Fill out the form, we'll be in touch.
  • Go over your options with an agent.
  • Get the coverage you need.

Would you rather discuss this in person? Get in touch with an agent today!

Contact Us