Hausman-Kunkel InsuranceHausman-Kunkel Insurance
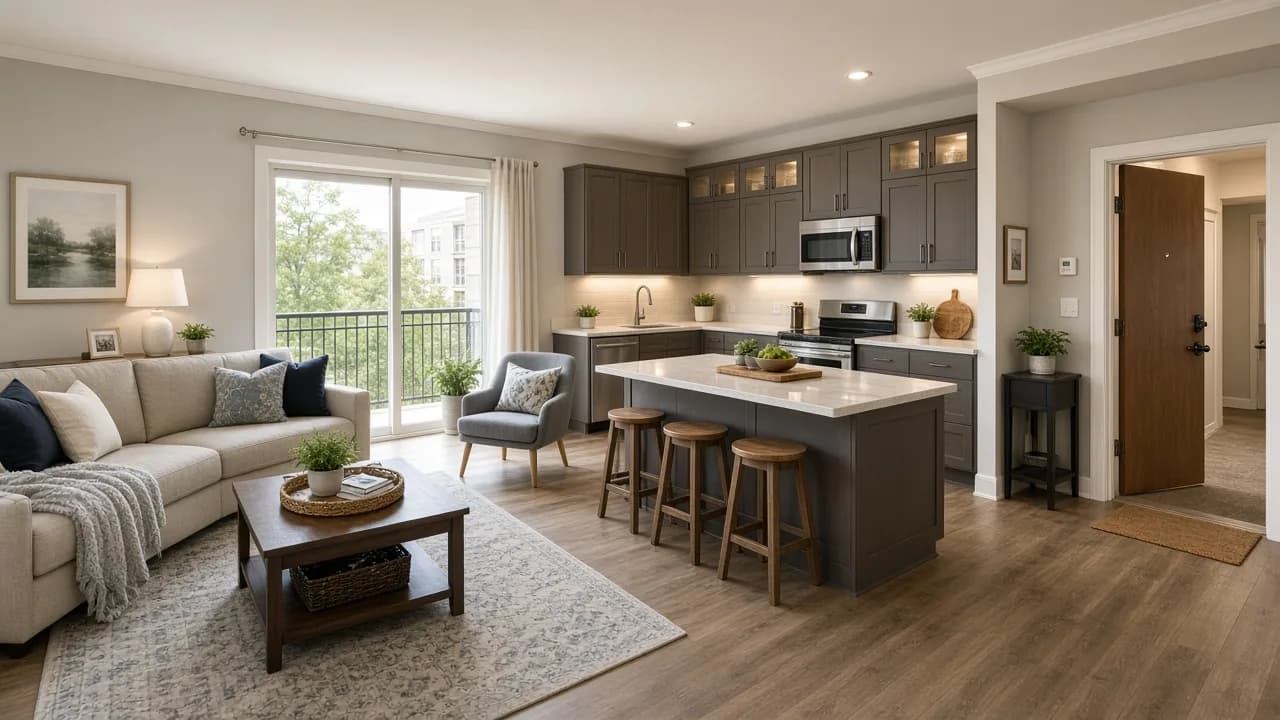
Owner-occupied Illinois condo living room with upgraded kitchen, balcony, belongings, and a shared hallway beyond the door

Condo Insurance

Get the protection you need for your apartment or condo

Walls-in vs the master

The association covers the shell; HO-6 covers your interior.

The master policy typically insures common elements and, depending on the bylaws, some of the unit. Your HO-6 is the walls-in policy for what the master does not pick up. Read the bylaws before you guess the limit.

Learn more →

Tap a point on the scene to learn more

Pin the add-ons that match how you use this coverage

The base condo policy is the printed form. An is a taped-on change — adding coverage, taking it away, or renaming who is insured. Optional coverages ride along with the policy. Separate policies sit beside it.

Form names and availability vary by carrier. This is a map of add-ons we commonly shop in Illinois — not a promise that every company offers every item.

Base policy

Condo policy

Hover an add-on to read it, then click to pin it here — a review list for your next conversation with an advisor.

Send this list to an advisor →We’ll open the contact form for this coverage so an advisor can help you decide which add-ons belong on the policy.

1 of 9

Endorsement

Loss assessment

Your share when the association bills owners after a building claim.

If a covered building loss exceeds the master — or the HOA is large — the board can assess unit owners. on the HO-6 is how that bill is meant to be handled. Association-deductible assessments may need their own limit. We read the bylaws with the .

The master condo policy typically protects only the shell of your unit, leaving your personal property and the unit interior at risk. We will match your HO-6 to the bylaws: (often walls-in), , , and if a covered makes the unit unlivable.

What does condo insurance cover?

Your condo association's insurance policy likely covers certain aspects of your condo, such as common or shared areas. As a result, it may cover your condo unit, but not any improvements you make or fixtures you add to the condo. It also will not cover your personal possessions. Condo insurance is designed to make up for this shortfall. It is a mixture of the better-known landlord insurance and renters insurance but is specially designed for your particular condo.

Protecting your personal property

Condo insurance covers your personal belongings inside your condo unit. That means everything from your appliances to your clothes will be covered in the event of a loss. Without it, you would have to replace your lost or damaged possessions out-of-pocket. Condo insurance also covers damage caused by theft, fire, severe wind, lightning strikes, and frozen pipes. It is important to note, however, that condo insurance does not usually cover flooding.

Liability coverage options

In addition to property coverage, condo policies may also include liability coverage. For example, if a guest is injured in your condo, it will pay for their medical expenses. It can also cover you in the case of a lawsuit if you are responsible for damages to another condo property. Living expenses may also be covered if there is damage to your condo unit that renders it unlivable.

Getting you the coverage you need for your condo

It can be confusing to figure out exactly what coverage you need for your condo unit, so we will work with you to find the condo insurance policy that is right for you. On top of that, we can show you just how inexpensive condo insurance is in comparison to the potential costs of replacing your personal belongings out-of-pocket.

We make the process straightforward and simple, going over what your condo association does not cover and how your policy can fill in the gaps. Reach out to our team when you are ready to review options. to discuss your condo insurance options.

Request a condo quote to get started.

Frequently Asked Questions

What does Condo Insurance typically cover in Illinois?
Policies usually address or contents, , and after a covered loss. Condo and renters plans differ in what the association or landlord covers versus what you must insure yourself.
Does Illinois home insurance cover sewer backup?
Standard HO policies may exclude sewer and drain backup. Chicagoland homes—especially older neighborhoods—often benefit from a .
How should I choose dwelling limits in the western suburbs?
Limits should reflect rebuild cost, not just market value or your mortgage balance. We help western suburbs homeowners review , , and as property values and construction costs change.
When should I review personal umbrella limits?
After buying a home, adding a teen driver, or increasing net worth. Illinois jury awards and medical costs make practical layer for many Chicagoland families.
What is an HO-6 versus the association master policy?
The master typically insures common elements and, depending on the bylaws, some of the unit. Your HO-6 is the walls-in policy for contents, unit , and whatever interior the master does not pick up. Bare-walls associations leave almost the entire interior on you. We match to the bylaws, not a generic apartment quote.
What is loss assessment on a condo policy?
If a covered building loss exceeds the master — or the HOA is large — the board can bill unit owners. on the HO-6 is how that share is meant to be handled. Association-deductible assessments may need their own limit. We read the bylaws with the , not after the first assessment letter.
Does condo insurance cover a remodeled kitchen or other upgrades?
Often yes, as improvements and betterments on the unit-owner form, especially in a bare-walls association. Cabinets, flooring, and fixtures you added after purchase frequently sit on the HO-6, not the master. A renters quote will understate that limit. We set building coverage from the remodel and the bylaws.
Does condo insurance cover sewer backup and flood in the unit?
Sewer and drain backup is often excluded until you add an . Flood from a rising body of water is typically excluded and may need a separate flood policy. Garden-level Chicagoland units see both after a storm. We do not treat flood and sewer as one coverage.
Does condo insurance cover the building exterior and common hallways?
Usually not. Exteriors, roofs, and common hallways are the association master’s job. Your HO-6 is the unit interior, your belongings, and tied to the unit. A slip in a shared hallway is more often the HOA’s GL. We split those so a claim is not argued between two policies.
How does an independent agency help me compare Condo options?
As an in Roselle, we compare Condo Insurance options from multiple carriers instead of a single company menu. That helps Illinois clients find coverage that fits their risks, contracts, and budget—with local follow-up when questions or claims come up.

Endorsements and add-ons

The same condo policy add-ons from the explorer above, listed out. Form names and availability vary by carrier.

Additional living expenses

Optional coverage

Hotel and extra costs if a covered loss makes the unit unlivable.

If a fire or other covered shuts your unit, can pay a hotel and extra costs while you cannot stay. The master may cover the building; it does not automatically house you. Limits and time caps still apply.

Flood

Separate policy

Rising water is typically excluded from the HO-6.

Flood from surface water, a river, or storm runoff is usually excluded. Units near a creek, a low garage, or a first-floor patio still need a separate flood policy. is a different .

Learn more →

Loss assessment

Endorsement

Your share when the association bills owners after a building claim.

If a covered building loss exceeds the master — or the HOA is large — the board can assess unit owners. on the HO-6 is how that bill is meant to be handled. Association-deductible assessments may need their own limit. We read the bylaws with the .

Personal injury

Endorsement

Libel, slander, and some invasion-of-privacy claims.

Some condo forms add personal injury by — alleged slander in a board dispute or an association group thread. It is not the same as guest . We add it when the bylaws and the building’s politics make it relevant.

Personal umbrella

Separate policy

Extra liability over the HO-6 after a severe guest claim.

A serious injury in the unit can exceed the condo limit. An sits over the HO-6 — and usually over auto. Illinois jury awards make this a practical layer for many western-suburbs owners.

Learn more →

Scheduled personal property

Endorsement

Lists jewelry, bikes, or instruments at agreed amounts.

Unscheduled contents usually cap jewelry and similar items. Scheduling an appraisal or invoice can raise those limits. Bring receipts. This is the same idea as a homeowners schedule, written on the HO-6.

Sewer backup

Endorsement

Water up through drains — especially garden-level units.

Sewer and drain backup is often excluded until you add an . Garden-level and first-floor Chicagoland condos see this after a storm. It is not flood from a rising body of water.

Learn more →

Unit building / improvements

Optional coverage

Walls-in coverage for interiors the master does not pick up.

on an HO-6 is not a house dwelling limit. It is walls-in: improvements, betterments, and whatever the bylaws leave to you. Bare-walls associations leave almost the entire interior on this line. We set it from the master and the remodel, not from a renters quote.

Ready for a Quote?

Speak with a local advisor who understands your coverage needs.

  • Geico insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • AAA insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Hartford insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Progressive insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Liberty Mutual insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Travelers insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Safeco insurance quotes through Hausman-Kunkel Insurance in Roselle, IL

Contact Hausman-Kunkel Insurance

As an independent agency, we are here to help you find the right coverage.

Please do not include sensitive, private information in this area.

Get a Quote

It only takes a minute to get started.

  • Fill out the form, we'll be in touch.
  • Go over your options with an agent.
  • Get the coverage you need.

Would you rather discuss this in person? Get in touch with an agent today!

Contact Us