Hausman-Kunkel InsuranceHausman-Kunkel Insurance
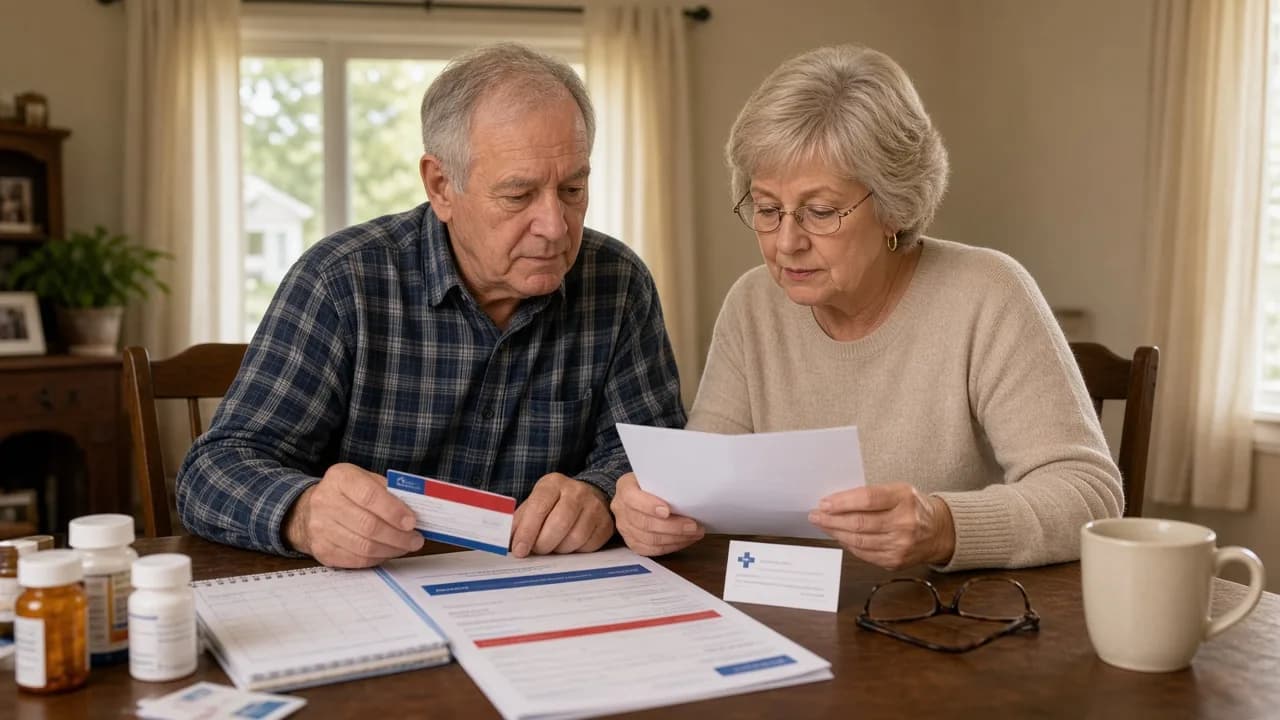
Older Illinois couple at a dining table with Medicare cards, medications, eyeglasses, and a calendar

Medicare

Helping you understand Medicare and its various options

Part A — hospital

Inpatient hospital, skilled nursing after a qualifying stay, and some hospice.

Most people get Part A -free if they or a spouse paid Medicare taxes long enough. It is not a blank check for every hospital bill. , days, and what counts as inpatient still matter. We walk Illinois clients through a typical stay before they assume “Medicare covers the hospital.”

Learn more →

Tap a point on the scene to learn more

Pin the add-ons that match how you use this coverage

The base medicare plan is the printed form. An is a taped-on change — adding coverage, taking it away, or renaming who is insured. Optional coverages ride along with the policy. Separate policies sit beside it.

Form names and availability vary by carrier. This is a map of add-ons we commonly shop in Illinois — not a promise that every company offers every item.

Base policy

Medicare plan

Hover an add-on to read it, then click to pin it here — a review list for your next conversation with an advisor.

Send this list to an advisor →We’ll open the contact form for this coverage so an advisor can help you decide which add-ons belong on the policy.

1 of 9

Optional coverage

Medigap (Medicare supplement)

Fills Part A and B deductibles and coinsurance when you keep Original Medicare.

Medigap sits on top of Parts A and B. You generally keep doctors who accept Medicare. The best time to buy without medical questions is a limited window around Part B. After that, can apply in Illinois. We compare standardized plan letters, not brand slogans.
Learn more →

Medicare plans and supplemental options have become more complex over time. Understanding Parts A, B, C, and D—and how add-ons fit together—helps you choose coverage with confidence.

We will compare , , and what happens during a if a payment is late so the plan you pick matches your doctors and budget.

Medicare options we help with

Whether you are approaching eligibility or reviewing your current plan, explore the topics below or speak with an advisor who can walk you through your choices.

We will help you evaluate your needs so you can make an informed decision.

Request a Medicare quote to get started.

Frequently Asked Questions

What are Medicare Parts A, B, C, and D?
Part A is hospital. Part B is medical. Part C is Medicare Advantage — a private plan that bundles hospital, medical, and often drugs. Part D is prescription coverage, either standalone or inside many Advantage plans. We map which combination matches your doctors and medications.
When is Medicare Annual Election Period?
AEP runs October 15 through December 7. Most people can switch Medicare Advantage or Part D for a January 1 start. Missing it usually means waiting unless another enrollment period applies. We treat mid-October in Roselle as a deadline.
Should I choose Medicare Advantage or a Medigap supplement?
Advantage uses networks and prior authorization and may include extras. Medigap sits on Original Medicare and generally lets you see doctors who accept Medicare. The right choice depends on specialists, travel, drugs, and whether you are still in a guaranteed-issue window. We compare both.
Do I need Part D if I take few prescriptions?
Often yes, or you need creditable drug coverage from work. Going without Part D can trigger a late-enrollment penalty that does not expire. Even a modest formulary plan can be cheaper than the penalty plus a later diagnosis. We match your list during AEP.
What is a Medicare late-enrollment penalty?
If you delay Part B or Part D without creditable coverage, Medicare can add a penalty that lasts. Employer coverage can delay the clock; COBRA and retiree plans need a closer look. We map your work coverage before you turn 65.
Does Original Medicare cover dental, vision, and hearing?
Generally not for routine care. Some Advantage plans add limited extras. Standalone dental, vision, and hearing policies still exist. We do not treat a small Advantage allowance as the quote your dentist actually gave.
I am still working. When should I enroll in Medicare?
It depends on employer size and whether your coverage is creditable. Enrolling late without a valid delay can mean penalties. Bring your work ID and the employer’s Medicare letter. We coordinate Medicare with the group plan instead of guessing.
Can I change Medicare plans outside Annual Election Period?
Sometimes. Moving, qualifying for extra help, certain trial rights, and other special periods can open a window. Most mid-year shopping still waits for AEP. Call before you assume you are stuck — or before you drop a plan.
What happens during a Medicare plan’s grace period if a premium is late?
Advantage and Part D plans can disenroll you after a missed if the runs out. Original Medicare Part B has its own rules. We go over premium, , and what a late payment does so the plan you pick matches your budget.
How does a local independent agency help with Medicare?
As an in Roselle, we compare Medicare Advantage, Part D, and supplement options from multiple carriers instead of a single company menu. That helps Illinois clients match doctors, drugs, and budget — with local follow-up when questions come up.

Endorsements and add-ons

The same medicare plan add-ons from the explorer above, listed out. Form names and availability vary by carrier.

ACA or short-term before 65

Separate policy

If you are not yet eligible for Medicare, individual health is a different conversation.

Medicare eligibility is age, disability, or ESRD — not a marketplace metal level. People under 65 still use ACA or, in limited cases, short-term medical. We do not enroll someone in Advantage who is not eligible. Bring your birthday and work coverage.

Learn more →

Annual Election Period

Optional coverage

October 15 through December 7 — switch Advantage or Part D for January 1.

AEP is the yearly window for most Medicare Advantage and Part D changes. Missing it usually means waiting unless another enrollment period applies. We treat mid-October in Roselle as a deadline. Bring doctors, drugs, and last year’s explanation of benefits.

Dental, vision, and hearing

Separate policy

Original Medicare generally skips routine extras. Advantage allowances are not unlimited.

Most routine dental, vision, and hearing care is outside Original Medicare. Some Advantage plans add capped extras. Standalone policies still exist. We do not treat a small dental allowance as the quote your dentist actually gave.

Learn more →

Final expense life insurance

Separate policy

A small permanent life policy meant for funeral and last bills.

Final expense is life insurance, not a Medicare benefit. It does not pay hospital . Families who want burial costs off the next generation get a separate life quote. We keep it off the Medicare comparison grid on purpose.

Learn more →

Hospital indemnity

Separate policy

A cash benefit for a hospital stay beside Medicare — not a substitute for Part A.

Hospital indemnity pays a scheduled amount per day or admission. It does not replace Part A, a supplement, or Advantage cost sharing. Some Illinois beneficiaries add it for they expect. We quote it as a sidecar, not as Medicare.

Learn more →

Late-enrollment penalties

Optional coverage

Delaying Part B or Part D without creditable coverage can raise premiums for good.

Medicare can add a penalty that does not expire if you go without Part B or creditable drug coverage too long. Employer coverage can delay the clock; COBRA and retiree plans need a closer look. We map work coverage before you turn 65.

Medicare Advantage (Part C)

Optional coverage

A private plan that bundles hospital, medical, and often drugs.

Advantage plans use networks and prior authorization. Extra benefits such as dental or hearing are limited and plan-specific. We check your specialists, hospitals, and drugs against the directory — not only the monthly — before anyone leaves Original Medicare.

Learn more →

Medigap (Medicare supplement)

Optional coverage

Fills Part A and B deductibles and coinsurance when you keep Original Medicare.

Medigap sits on top of Parts A and B. You generally keep doctors who accept Medicare. The best time to buy without medical questions is a limited window around Part B. After that, can apply in Illinois. We compare standardized plan letters, not brand slogans.

Learn more →

Part D prescription coverage

Optional coverage

Standalone drug coverage, or the drug benefit inside many Advantage plans.

Formulary, tiers, and your pharmacy decide whether Part D is affordable. The Inflation Reduction Act capped annual out-of-pocket spending on Part D drugs; the dollar amount is set each year. We match your medication list during Annual Election Period.

Learn more →
Ready for a Quote?

Speak with a local advisor who understands your coverage needs.

  • Geico insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • AAA insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Hartford insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Progressive insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Liberty Mutual insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Travelers insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Safeco insurance quotes through Hausman-Kunkel Insurance in Roselle, IL

Contact Hausman-Kunkel Insurance

As an independent agency, we are here to help you find the right coverage.

Please do not include sensitive, private information in this area.

Get a Quote

It only takes a minute to get started.

  • Fill out the form, we'll be in touch.
  • Go over your options with an agent.
  • Get the coverage you need.

Would you rather discuss this in person? Get in touch with an agent today!

Contact Us