Hausman-Kunkel InsuranceHausman-Kunkel Insurance
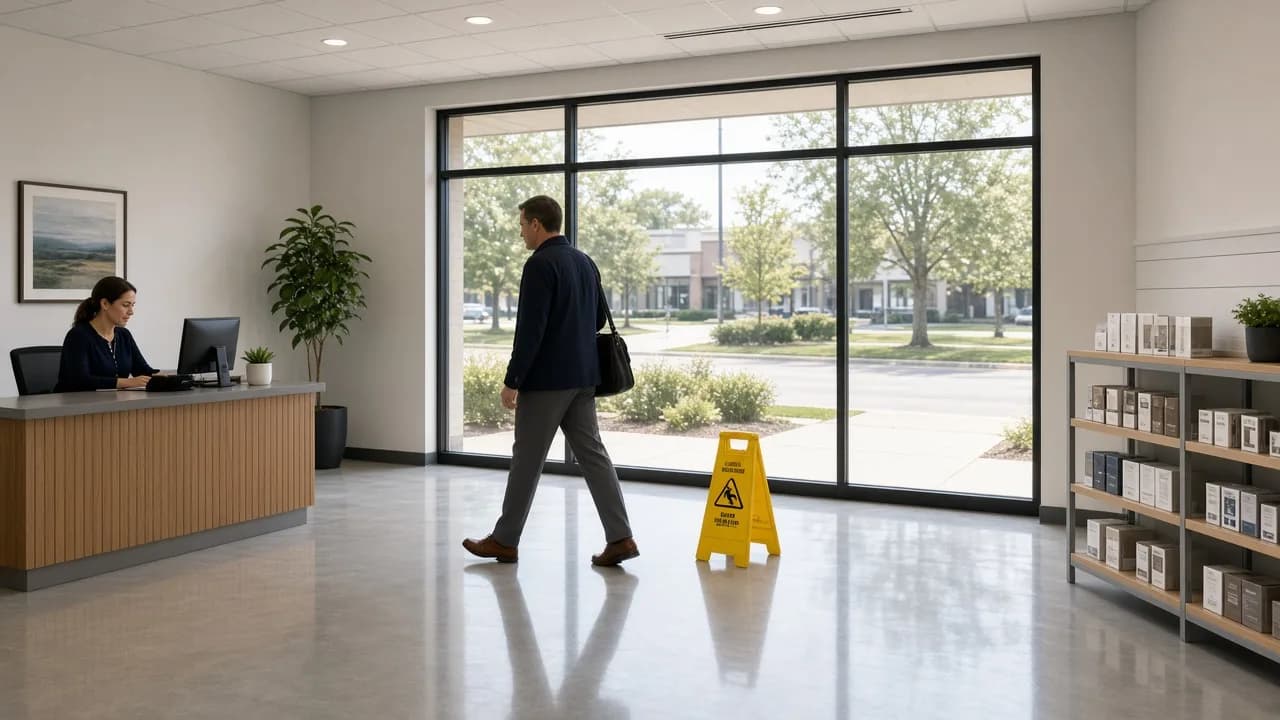
Suburban Illinois office lobby with a receptionist, a visitor, a wet-floor sign, product shelves, and a sidewalk beyond the glass

General Liability Insurance

Comprehensive protection that keeps up with your industry

Premises injury

A visitor slips in the lobby — that is why GL exists.

Premises responds when a customer, vendor, or guest is hurt on your property. Illinois storefronts and offices start here. It is not , and it is not a medical-payments substitute for employees.

Learn more →

Tap a point on the scene to learn more

Pin the add-ons that match how you use this coverage

The base general liability policy is the printed form. An is a taped-on change — adding coverage, taking it away, or renaming who is insured. Optional coverages ride along with the policy. Separate policies sit beside it.

Form names and availability vary by carrier. This is a map of add-ons we commonly shop in Illinois — not a promise that every company offers every item.

Base policy

General liability policy

Hover an add-on to read it, then click to pin it here — a review list for your next conversation with an advisor.

Send this list to an advisor →We’ll open the contact form for this coverage so an advisor can help you decide which add-ons belong on the policy.

1 of 10

Endorsement

Additional insured

Landlord or project owner named on liability as the contract requires.

Leases and vendor packets specify additional-insured wording. It has to live on the policy. The certificate only reports it. We read the insurance exhibit instead of guessing so a Chicagoland landlord’s first request is not a coverage fight.
Every business faces uncertainty. We work with you to identify your risks and assemble a commercial insurance package that makes sense for how you operate.

Protection when others hold you responsible

You already protect your buildings, equipment, and staff. addresses a different risk: harm to other people or their property that your business may cause—and the lawsuits that can follow.

What general liability covers—and what it does not

General liability primarily covers to people outside your business and damage to their property. It generally does not cover professional mistakes; for that, (E&O) insurance is the right tool. Data breaches and reputational harm may also fall outside a standard GL policy.

When your business needs GL coverage

If you meet clients at your location or theirs, work on someone else's property, or need proof of insurance to sign a contract, general liability is often essential. Many vendors, landlords, and project owners require it before work begins.

We help you find limits and that match your contracts and operations. Request a general liability quote to get started.

Frequently Asked Questions

What does general liability insurance cover?
GL typically covers third-party , , and personal or advertising injury claims arising from your operations. It is often the first line of defense when a customer, vendor, or visitor is injured on your premises.
What limits do Chicagoland contracts usually require?
Many leases and vendor agreements specify minimum per-occurrence and aggregate limits. We align GL limits with your contracts, leases, and Illinois regulatory expectations rather than selling generic templates.
How quickly can I get a certificate of insurance?
Most active clients receive ACORD certificates the same business day. We know Chicagoland vendors and landlords often need proof before you start work.
What common claims do Illinois businesses face under general liability?
Slip-and-fall injuries, damage to a client's property, and advertising injury allegations are frequent examples. Limits and should reflect how and where your business operates.
Do leases require additional insured wording on general liability?
Often yes. Chicagoland landlords and project owners specify , , and sometimes primary wording. Those live on the policy. The certificate only reports them. We read the insurance exhibit and match the form instead of hoping the ACORD is enough.
Does general liability cover employees driving personal cars for work?
No. stays on the premises. A bank run or a supply trip in a personal car is hired and — usually an on a or a separate auto form. Personal auto policies often exclude business use. A true work fleet belongs on commercial auto.
Does general liability cover professional mistakes or errors and omissions?
Typically not. GL is and to others — a visitor fall, not bad advice. Accountants, consultants, and similar professions need a separate professional- or policy. Mixing those facts into a GL claim is a common surprise. We split them when the work is advice, not a storefront.
Is a product claim the same as a slip-and-fall on general liability?
No. Premises is someone hurt at your location. Products and completed operations are harm from what you sold or work you already finished — after the customer leaves. Some GL forms include a products limit; others need it confirmed. Contractors and sellers should not assume it is automatic.
Does general liability cover liquor, workers compensation, or cyber?
No. Selling drinks is typically excluded and may need liquor . Employee injuries sit on . A ransomware event is a cyber policy, not a premises claim. Illinois employers, restaurants, and offices still need those as separate conversations. We do not stretch GL across them.
Why use an independent agency for General Liability Insurance?
As an in Roselle, we compare Insurance options from multiple carriers instead of a single company menu. That helps Illinois clients find coverage that fits their risks, contracts, and budget—with local follow-up when questions or claims come up.

Endorsements and add-ons

The same general liability policy add-ons from the explorer above, listed out. Form names and availability vary by carrier.

Additional insured

Endorsement

Landlord or project owner named on liability as the contract requires.

Leases and vendor packets specify additional-insured wording. It has to live on the policy. The certificate only reports it. We read the insurance exhibit instead of guessing so a Chicagoland landlord’s first request is not a coverage fight.
Cyber liability

Separate policy

Stolen card data is not a premises burglary claim.

A ransomware event on the register or a stolen customer list is not GL. Cyber sits beside the form, usually as its own policy. We do not treat a data breach as a slip-and-fall.

Learn more →

Damage to premises rented to you

Optional coverage

Fire or similar damage to a space you occupy but do not own.

Tenants often need this GL sublimit for damage to the rented premises. It is not a substitute for commercial property on your contents and improvements. Read the lease — many western-suburbs landlords still require both.

Liquor liability

Separate policy

Selling drinks is typically excluded from GL.

If you sell alcohol, usually excludes liquor. Illinois dram-shop exposure does not shrink because food is most of the check. Host liquor for a holiday party is not a bar program. That is a separate policy.

Learn more →

Primary and noncontributory

Endorsement

Your GL pays first so the landlord’s policy is not asked to share.

Many additional-insured still leave the other party’s policy in play. Primary and noncontributory wording is the usual lease ask so your GL responds first. It is an endorsement, not a sentence on the certificate.

Products / completed operations

Optional coverage

Claims after the customer leaves or the job is finished.

Premises GL is the lobby slip. Products and completed operations are harm from what you sold or work you already finished. Some forms include a limit; others need it confirmed. Contractors and sellers should not assume it is automatic.

Waiver of subrogation

Endorsement

Your insurer will not chase the other party after a paid claim.

Illinois leases routinely require a on GL. Without the , a premises or property payment can still become a recovery action against the landlord. Match the exhibit line by line.

Workers compensation

Separate policy

Employee injuries are not general liability.

Illinois employers with employees generally need . GL pays third parties, not payroll injuries. Landlords still ask for both on the certificate. We place them as a pair.

Learn more →

Ready for a Quote?

Speak with a local advisor who understands your coverage needs.

  • Geico insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • AAA insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Hartford insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Progressive insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Liberty Mutual insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Travelers insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Safeco insurance quotes through Hausman-Kunkel Insurance in Roselle, IL

Contact Hausman-Kunkel Insurance

As an independent agency, we are here to help you find the right coverage.

Please do not include sensitive, private information in this area.

Get a Quote

It only takes a minute to get started.

  • Fill out the form, we'll be in touch.
  • Go over your options with an agent.
  • Get the coverage you need.

Would you rather discuss this in person? Get in touch with an agent today!

Contact Us